Device locking solutions are changing how companies manage repayment risk in device financing.
M-KOPA’s 2025 Report shows the scale at which this model is already operating: it has supported 4.5 million smartphone users in Kenya, including 2.1 million first-time smartphone owners. Likewise, in the Philippines, Skyro has completed two million product-loan transactions through a network that includes 10,000+ partner stores and smartphone brands such as HONOR, TECNO, and Infinix.
However, financing more devices also creates a larger repayment portfolio to monitor. Manual follow-ups, disconnected collection systems, and field recovery cannot provide consistent control across millions of financed assets.
This is where Datacultr’s device locking becomes important. It gives financing companies a digital risk control layer that can support their portfolio growth while reducing manual work.
Let’s take a closer look.
[Also Read: Device Lock Tech: Securing the Future of Mobile Financing for NBFCs]
What Is Device Locking and How Does It Work?
Device locking technology connects the repayment status of a financed device with the borrower’s access to it. If the payment remains overdue, the device can be remotely locked. And it can be unlocked once the payment is confirmed.
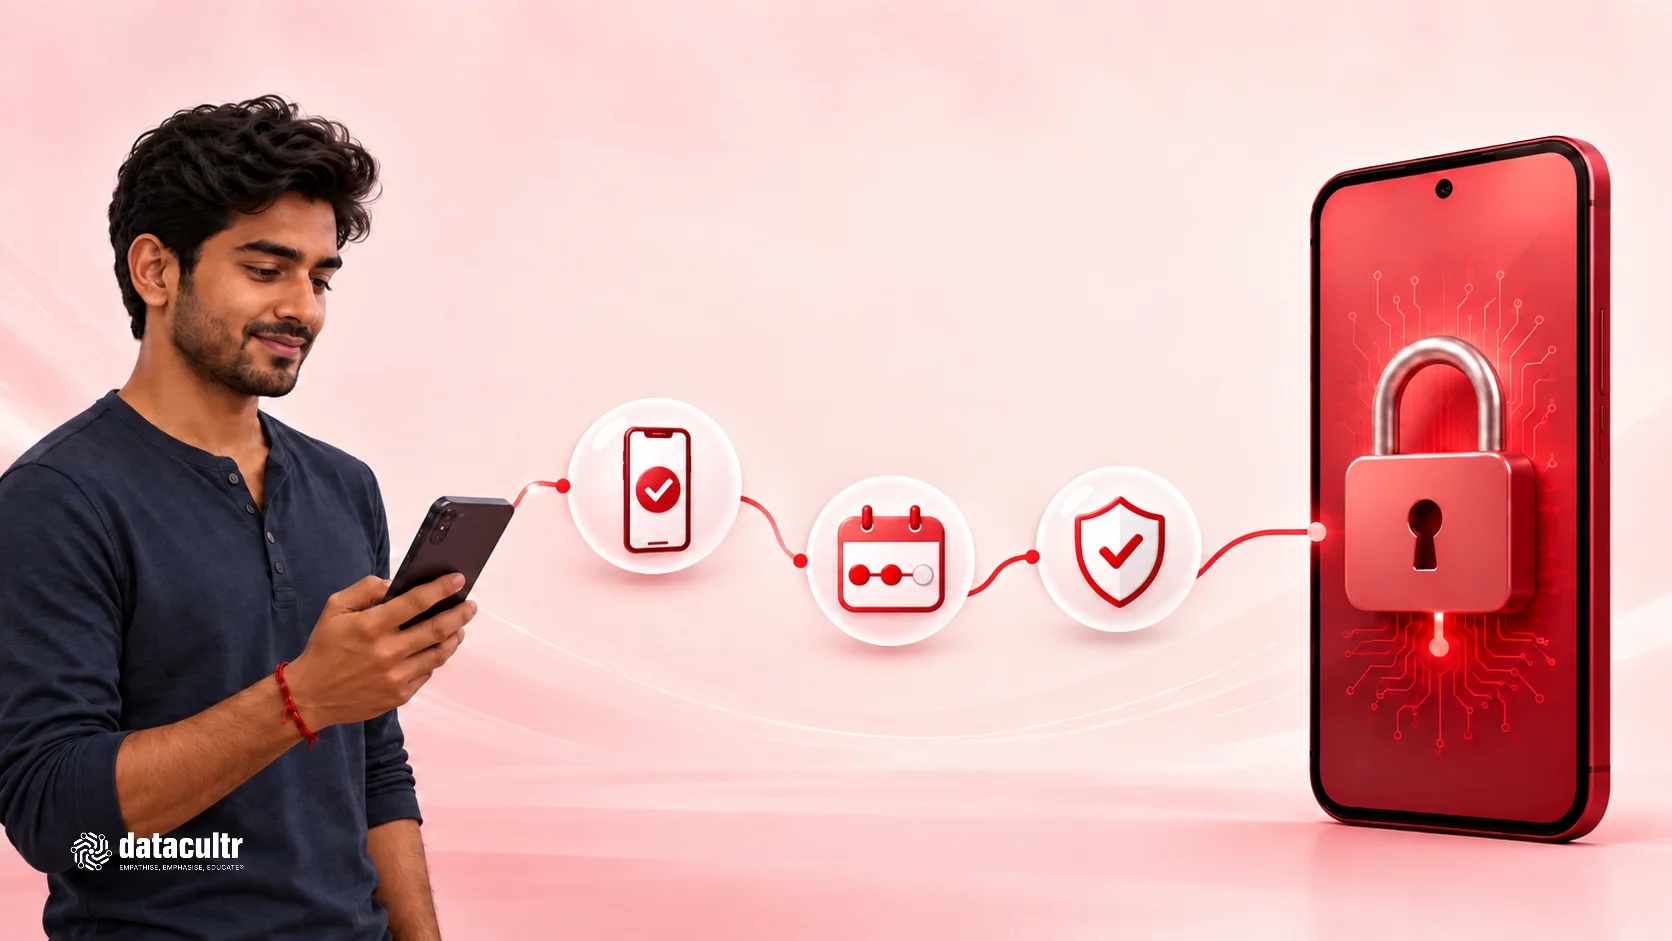
The process follows a simple sequence:
Reminder sent → Payment remains unpaid → Device locked → Payment confirmed → Device unlocked
Datacultr enables this process through Odyssey, its device financing risk management platform. The platform helps financial institutions, fintechs, telecom operators, retailers, and lenders manage repayment risk across smartphones, tablets, laptops, smart TVs, air conditioners, and other consumer durables. The device locking solution used within each financing program depends on the type of device and the risks involved.
Different Types of Device Locks and the Risks They Manage
Non-payment is only one risk associated with a financed device. A borrower may also keep the device offline, replace the bundled SIM, or move it to another telecom network. Datacultr’s device locking solution provides a specific control for each situation:
Device Lock
Restricts access when payment remains overdue. The lock screen can display the amount due, payment options, and support details.
Offline Lock
Applies a pre-scheduled lock even when the financed device is disconnected from the internet. Offline lock prevents overdue borrowers from avoiding a device lock by keeping the device offline.
SIM Lock
Binds the financed device to the bundled SIM and automatically locks the device if that SIM is removed or replaced.
Network Lock
Binds the financed device to the telecom operator’s network and restricts access if it is moved to another network.
Together, these controls manage repayment, connectivity, SIM, network, and offline-enforcement risks.
Device Locking: An Integral Part of a Wider Risk Control Strategy
Device locking should not be the first response to a missed payment. Datacultr’s progressive approach uses pre-due, due-date, and post-due communication to give borrowers multiple opportunities to pay. If the payment remains overdue, device access can then be restricted in stages.
[Also Read: The Future of Collections: Predictive, Proactive, Pre-Due]
Before restricting access, companies can use Datacultr’s customer engagement platform, TrueDigi, to contact borrowers, understand their intent, and guide them towards payment.
For example, TruCall enables direct-to-device calls, while TruPromise helps record and manage promise-to-pay commitments. For borrowers who remain unresponsive, TruNotice delivers compliant notices, while skip-tracing tools can help reconnect with them.
Together, TrueDigi and Odyssey help companies manage each stage of the post-due journey through communication, device locking, and further escalation.
Device Locking for the Next Phase of Device Financing
Device financing is expanding beyond smartphones. Tablets, laptops, smart TVs, air conditioners, and other connected devices can now be offered through instalment, PayGo, and subscription models.
Datacultr has supported more than 25 million loan journeys across 35+ markets. Through Odyssey, companies can manage device locking across different device categories and financing models through one infrastructure layer.
The opportunity is not simply to finance more products. It is to build a portfolio where repayment communication, device locking, and recovery actions remain manageable as the business expands across markets and device categories.
See how Datacultr has helped companies manage repayment risk and scale device financing. Explore Our Case Studies.
People Also Ask
Who Can Use Datacultr’s Device Locking Technology?
Banks, NBFCs, microfinance institutions, telecom operators, device manufacturers, retailers, and leasing companies can use Datacultr’s device locking technology to manage repayment risk across financed smartphones, tablets, laptops, smart TVs, air conditioners, and other connected devices.
Can device locking replace credit underwriting?
Device locking is a post-due risk management solution, while credit risk analysis is an important pre-loan process that should not be overlooked. It supports credit underwriting by helping financiers and NBFCs manage repayment risk after a device loan has been approved.
How does Datacultr’s device locking solution protect borrower privacy?
Datacultr’s device locking solution uses a Zero-PII architecture, enabling financing companies to manage repayment-linked device controls, without collecting or storing borrowers’’ personally identifiable information.
About Datacultr:
Datacultr provides digital risk management and customer engagement infrastructure to leading banks, NBFCs, fintechs, telcos, OEMs, and retail chains across 35+ countries. It enables secure device financing, microfinance, and Device as a Service (DaaS) programs while supporting millions of smartphones, tablets, laptops, smart TVs, ACs, and other consumer durables.